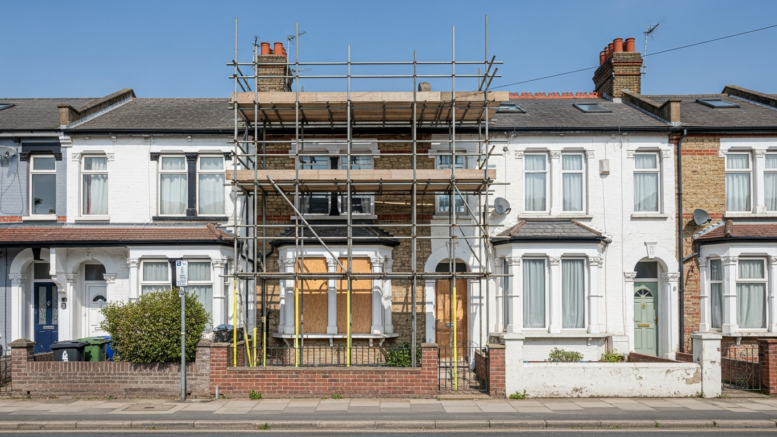
The cost of bringing Britain’s vacant housing stock back into use has climbed sharply, with new analysis from BuildLoan putting the bill at £34bn – up 19 percent year on year. For landlords and buy-to-let investors looking at refurbishment-led acquisitions, that matters for two reasons: empty homes still offer opportunity, but the entry cost is moving higher just as funding routes are changing.
Vacant stock still looks investable for landlords
BuildLoan said the average cost of renovating an uninhabitable property is now around £70,000, rising to as much as £95,000 for long-term vacant homes. The firm said there are around 360,000 long-term vacant properties across the UK, up 15 percent from 2025 based on its analysis of official data.
That leaves landlords with a familiar calculation. Refurbishment projects can still produce better yields than standard turnkey stock, especially in tighter local markets, but the margin for error is getting thinner. A higher works bill means more cash tied up before a property earns rent, and it raises the risk that smaller investors either overpay for stock or underbudget for the work needed to make it lettable.
Landlord Knowledge has already reported on calls for empty homes reform as 359,000 properties sit vacant, and on rising use of bridging finance to target vacant housing. The latest BuildLoan figures add a harder cost warning to that trend: there may be stock to buy, but getting it ready is becoming more expensive.
BuildLoan targets the funding gap on heavier refurb projects
The other part of the story is finance. BuildLoan has launched a new range of renovation products aimed at homes that have often fallen into the space between ordinary residential mortgages and short-term bridging loans. It said the range is intended for lighter, non-structural works and is funded by lenders including Chorley Building Society, Furness Building Society and Stafford for Intermediaries.
For landlords, that could widen the number of deals that stack up. Bridging remains useful where speed matters, but it can be expensive and unforgiving if works drift. A renovation product that sits between mainstream lending and bridging may help landlords tackle lower-grade stock without taking on full development finance risk.
The catch is that stronger funding options do not remove the pricing pressure. If more buyers can finance the same kind of stock, competition can push purchase prices higher. That means the headline gain is not simply easier borrowing – it is better choice for disciplined investors who know their numbers.
Higher costs could favour better prepared landlords
This follows Landlord Knowledge’s recent report on vacant homes and pressure for reform, which highlighted how much unused housing remains outside the rental market. The latest figures suggest the opportunity is still there, but it is shifting towards landlords with clearer refurb budgets, stronger cash buffers and access to specialist finance.
A practical warning stands out here. Rising renovation costs do not just affect major conversions. They also raise the risk on modest refurbishments where landlords have relied on thin margins, optimistic contractor quotes or short void assumptions. In that sense, the market may move further towards professional operators who can price risk properly.
What this means for landlords
- If you’re targeting empty homes: build in more headroom for works, delays and refinancing costs than you might have done a year ago.
- Watch for: local markets where vacant stock is plentiful but resale competition is limited – the finance may work, but the exit still has to.
- Bottom line: empty homes remain a route into stronger yields, but rising refurb costs mean sloppy underwriting will get punished faster.
Editor’s view
Refurbishment-led investing still makes sense, but only for landlords who treat it like a business rather than a punt. A bigger finance menu helps, yet the real edge now is cost control.
Author: Editorial Team – UK landlord & buy-to-let news, policy, and finance
Published: 5 May 2026
Sources: BuildLoan, ONS data analysis
Related reading: Propertymark calls for empty homes reform as 359,000 properties sit vacant