

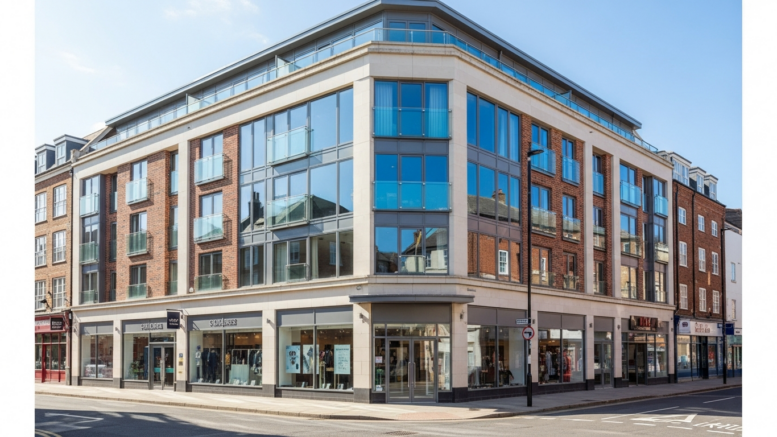
Ultimate Finance has opened its semi-commercial bridging loan to its full UK broker network after a pilot, widening funding options for landlords and investors buying or refinancing mixed-use property.
The lender said the product offers up to £4m for properties with both residential and commercial space, covering purchases, refurbishment, refinancing and development exits. That matters because mixed-use deals often fall between standard residential and commercial criteria, leaving landlords with fewer routes to finance when timing is tight.
For landlords, the move adds another sign that specialist lenders are pushing deeper into parts of the market that mainstream buy-to-let products do not always serve well. Investors looking at flats above shops, part-commercial blocks or value-add refurbishment cases may find the wider broker rollout makes these deals easier to place, even if pricing still needs close scrutiny.
Mixed-use demand pushes lenders beyond standard buy-to-let
Ultimate Finance said it built the proposition after broker feedback and a change in deal flow. The lender said semi-commercial transactions can sit in a gap between residential and commercial underwriting, limiting options for brokers and their clients.
That gap matters for smaller landlords as well as larger investors. Mixed-use stock can offer stronger yields or a lower entry price than pure residential assets, but funding is often harder to arrange because lenders need to assess the commercial element, the lease structure and the exit route.
Ultimate said it has originated £49m of new business so far this year. Liam Cavanagh, head of bridging finance at Ultimate Finance, said the pilot showed there was “consistent demand for a clear, practical semi-commercial bridging proposition” and said the wider launch reflected where brokers needed support.
Landlords still need to weigh cost, exit and asset type
The wider distribution does not mean every mixed-use deal will stack up. Bridging remains expensive compared with mainstream term lending, so landlords need a credible refinance or sale exit and a clear view of how quickly any refurbishment or title work can be completed.
Asset type will matter too. A flat above a stable retail unit is a different risk from a more management-heavy parade, and valuation appetite can change quickly if the commercial income is weak or vacant. Landlords using short-term finance in this corner of the market still need to test their numbers against slower exits and higher fees.
This follows Landlord Knowledge’s report on the £34bn vacant-home renovation funding gap, which highlighted growing demand for specialist products beyond standard buy-to-let. Alongside GB Bank’s move to widen distribution of its core buy-to-let range through Xplan Mortgage, the latest launch suggests lenders are still targeting harder-to-place landlord cases rather than retreating from them.
Landlords can read Ultimate Finance’s product announcement here.
What this means for landlords
- If you’re buying mixed-use property: finance options may be widening, but the deal still needs a clear exit and enough margin to absorb bridging costs.
- Watch for: how lenders price semi-commercial risk where the commercial unit is vacant, short-let or in a weaker secondary location.
- Bottom line: wider distribution is useful, but specialist finance only helps if the asset, timescale and refinance plan are realistic.
Editor’s view
Semi-commercial finance is not a mass-market landlord story, but it is a useful one. When lenders keep adding routes into awkward cases, it usually signals they still see enough investor demand in parts of the market that need more than a plain buy-to-let fix.
Author: Editorial Team – UK landlord & buy-to-let news, policy, and finance
Published: 24 June 2026
Sources: Ultimate Finance
Related reading: Vacant home renovation bill hits £34bn as finance gap narrows









