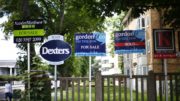
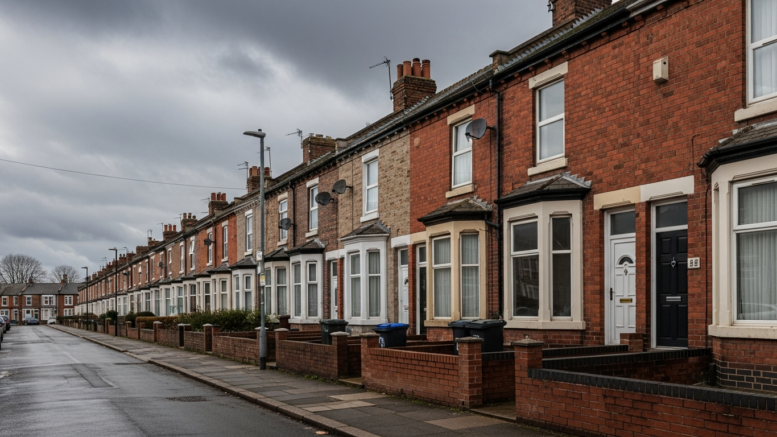
Buy-to-let investors can no longer assume residential property will beat inflation or outperform mainstream investments, according to new research from Rathbones, which says the long boom in UK property returns is over.
The wealth manager found that since 2016, UK residential property has returned about 3.7 percent a year – only just keeping pace with inflation – while London housing has lagged inflation altogether at 1.3 percent a year. Over the same period, Rathbones said a mixed portfolio of 25 percent UK equities and 75 percent international equities would have turned £100 into £174, against £134 for UK property and just £111 for London property.
For landlords, that does not mean buy-to-let has stopped working. It does mean capital growth can no longer be treated as the automatic rescue plan when tax, borrowing costs and compliance bills are squeezing net returns.
Rathbones says the property boom years have passed
Rathbones said the golden age for property investment ran from 1980 to 2016, when UK house prices rose by an average 6.7 percent a year and London values by 8.5 percent. It argues that backdrop has changed because the long fall in interest rates will not be repeated, housebuilding is rising and government policy has become less friendly to residential investors.
Its latest property investment research points to a tougher environment for landlords who bought on the assumption that future price growth would cover weak cashflow. In that sense, the report is less a verdict on housing itself than a warning against relying on one asset class to do everything.
That sits alongside Landlord Knowledge’s recent reporting on void costs hitting £1,135 as empty days squeeze returns and on hidden landlord costs piling up for smaller investors. The latest Rathbones figures push the same message from a different angle: the margin for mistakes is thinner when growth is slower.
Why landlords should focus on income, not hope
Rathbones said it is hearing more often from owners of second homes and buy-to-lets who are asking whether to sell and reinvest elsewhere. That will not be the right answer for every landlord. Rental income, borrowing structure and local demand still matter, and some regional markets remain far stronger than others.
But the report does sharpen one hard truth for landlords. If a property only works when prices are rising fast, it may not be a strong investment at all. In a slower-growth market, financing costs, voids, maintenance and tax take a bigger bite because there is less capital uplift to hide them.
This follows Landlord Knowledge’s recent coverage of landlords selling three homes for every one they buy and of more investors revisiting costs line by line. The latest research suggests that trend is not just about regulation fatigue. It is also about a colder investment calculation than many landlords had to make in the last cycle.
What this means for landlords
- If you’re reviewing a marginal property: stress-test it on rent, costs and voids rather than assuming future house price gains will bail it out.
- Watch for: markets where yields stay solid but capital growth slows, because those areas may still suit income-focused investors.
- Bottom line: buy-to-let can still work, but landlords need a business case, not a nostalgia trade.
Editor’s view
Too many landlords still talk about capital growth as if it is a law of nature. It is not. The investors who do best from here are likely to be the ones who underwrite deals on present-day cashflow, not on old stories about house prices only going one way.
Author: Editorial Team – UK landlord & buy-to-let news, policy, and finance
Published: 17 June 2026
Sources: Rathbones
Related reading: Void costs hit £1,135 as empty days squeeze landlords