Castle Trust Bank has cut buy-to-let mortgage and refurbishment rates, but says the repriced deals are only open to cases that complete by 31 August.
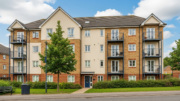
The lender said standard buy-to-let pricing now starts at 5.69 percent up to 70 percent gross loan-to-value, with rates from 5.74 percent at 75 percent LTV. Large HMOs and refurbishment products were also repriced, giving landlords a clear summer deadline as well as lower headline rates.
For landlords, the fresh point is the deadline as much as the pricing. Time-limited repricing can pull refinancing and purchase decisions forward, especially for investors trying to line up summer completions before any further movement in funding costs.
Buy-to-let and refurbishment pricing both moved lower
On the short-term side, Castle Trust said light refurbishment bridging now starts at 0.7 percent per month across all LTV bands, with drawdown cases from 0.77 percent per month. Heavy refurbishment bridging has been cut to 0.99 percent per month across all LTVs.
That widens the story beyond a routine buy-to-let tweak. Landlords working on upgrades, conversions or reletting plans now have another sign that lenders are still chasing specialist business, not just plain-vanilla remortgages.
This follows Landlord Knowledge’s recent coverage of lenders cutting buy-to-let rates before the remortgage rush, which showed competition was already intensifying across the sector. Castle Trust’s latest move adds a deadline that could make decision timing more important over the next ten weeks.
Why the August deadline matters now
The lender said the new pricing only applies to cases completing by the end of 31 August 2026. That is a narrow enough window to matter for landlords with valuation, legal or works timelines still to manage.
It also comes just days after Landlord Knowledge reported Castle Trust’s move to drop physical valuations on standard buy-to-let cases up to £750,000, a change designed to speed up applications. Taken together, the message is clear: the bank wants landlords and brokers to move faster through both pricing and process.
Landlords should still look past the headline rate. Gross and net LTV treatment, product fees, exit strategy on refurbishment cases and whether a summer completion is realistic may matter more than a small change in the opening number. Further product detail is available from Castle Trust Bank.
What this means for landlords
- If you’re refinancing this summer: a hard completion deadline means paperwork and valuation timing now matter as much as rate shopping.
- If you’re buying HMOs: the revised pricing keeps specialist stock in play, but check the full cost structure.
- If you’re funding works: lower refurbishment bridging rates may improve viability on quicker turnaround projects.
- Watch for: other lenders responding with short-window repricing as competition builds through summer.
- Bottom line: cheaper rates help, but only if the deal can actually complete before the deadline.
Editor’s view
Limited-period pricing is useful only when it is real-world usable. The interesting part here is Castle Trust pairing lower rates with faster processing changes, which suggests lenders know landlords are running out of patience with deals that look good on paper but drift in practice.
Author: Editorial Team – UK landlord & buy-to-let news, policy, and finance
Published: 16 June 2026
Sources: Castle Trust Bank
Related reading: Castle Trust drops physical valuations on standard BTL up to £750,000